


Need extra housing market tales from Lance Lambert’s ResiClub in your inbox? Subscribe to the ResiClub newsletter.
Through the pandemic housing increase, housing demand surged quickly amid ultralow rates of interest, stimulus, and the distant work increase—which elevated demand for area and unlocked “WFH arbitrage” as excessive earners had been capable of preserve their revenue from a job in, say, NYC or L.A., and purchase in, say, Austin or Cape Coral-Fort Myers, Florida. Federal Reserve researchers estimate “new building would have needed to enhance by roughly 300% to soak up the pandemic-era surge in demand.”
In contrast to housing demand, housing stock supply isn’t as elastic and may’t ramp up as shortly. In consequence, the heightened pandemic period demand drained the market of energetic stock and overheated residence costs, with U.S. home prices rising a staggering 43% between March 2020 and June 2022.
Whereas many commentators view energetic stock and months of provide merely as measures of “provide,” ResiClub sees them extra as proxies for the supply-demand equilibrium. As a result of housing demand is extra elastic than housing inventory, giant swings in energetic stock or months of provide are often pushed by shifts in demand.
For instance, throughout the pandemic housing increase, surging demand triggered houses to promote sooner—pushing energetic stock down, at the same time as new listings remained regular. Conversely, in recent times, weakening demand has led to slower gross sales, inflicting energetic stock to rise—at the same time as new listings fell under pattern.
Certainly, throughout the ravenous housing demand on the peak of the pandemic housing increase in April 2022, virtually your complete nation was not less than 50% under pre-pandemic 2019 energetic stock ranges.
Brown = Lively housing stock on the market in June 2021 was under pre-pandemic 2019 ranges
Inexperienced = Lively housing stock on the market in June 2021 was above pre-pandemic 2019 ranges
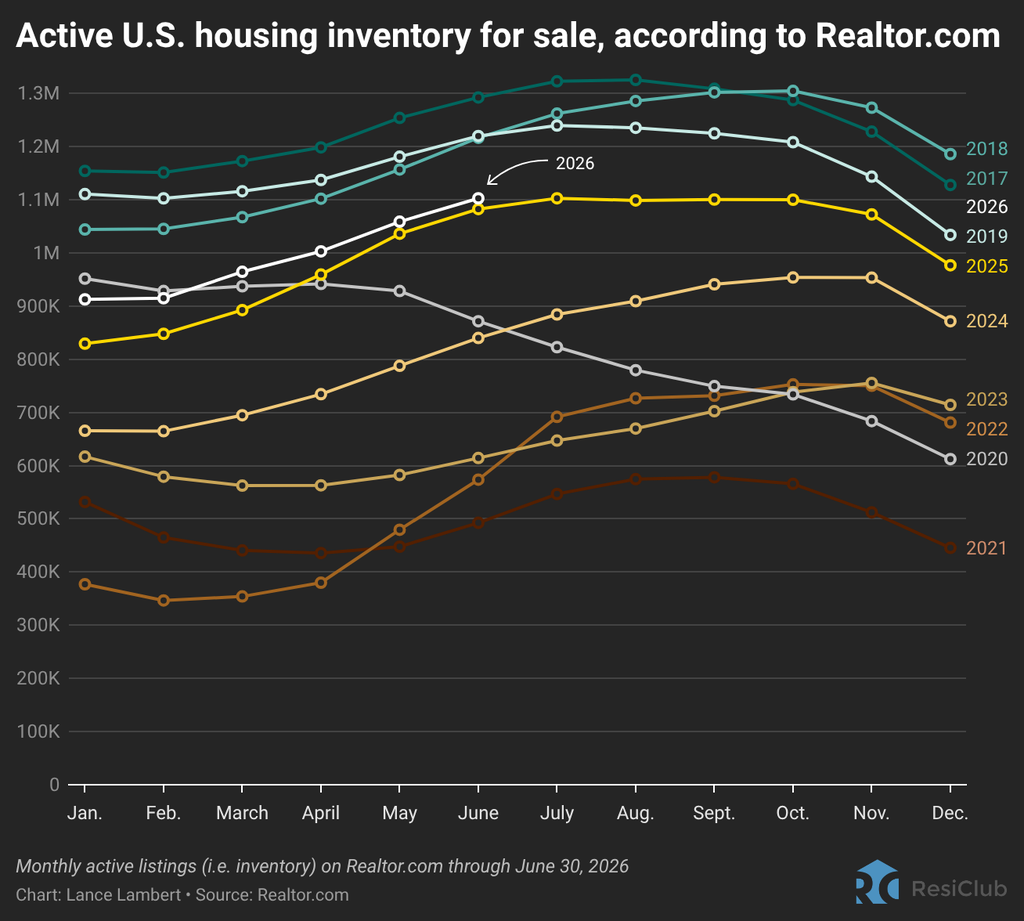
After all, now it’s a unique image: Nationwide energetic stock is on a multiyear rise (even when just lately the tempo has slowed to only a crawl).
Not lengthy after mortgage charges spiked in 2022—inflicting affordability to mirror the fact of the sharp residence worth will increase throughout the pandemic housing increase—and return-to-office mandates gained momentum, nationwide demand within the for-sale market pulled again and the pandemic housing increase fizzled out.
Initially, within the second half of 2022, that housing demand pullback triggered a “fever breaking” in quite a lot of markets—notably in rate-sensitive West Coast housing markets and in pandemic boomtowns like Austin and Boise, Idaho—inflicting energetic stock to spike and pushing these markets into correction mode within the second half of 2022.
Heading into 2023, a lot of those self same Western and pandemic boomtown markets (excluding Austin) stabilized, because the spring seasonal demand—coupled with still-tight energetic stock ranges—was sufficient to quickly agency up the market. For a bit, the nationwide energetic stock stopped rising 12 months over 12 months.
Nevertheless, that interval of nationwide stock stabilization didn’t final. Amid nonetheless slumped housing demand, nationwide energetic stock started to rise once more—and we’re now within the midst of a 32-month streak of year-over-year will increase in nationwide energetic listings. (Nevertheless, national inventory development has decelerated just lately from +28.9% year-over-year nationwide stock development at the moment final 12 months to simply +1.9% 12 months over 12 months between June 2025 and June 2026.)
This era of stock rebound has coincided with nationally aggregated year-over-year current residence worth development throughout most indices slowing to round +1.0%. Whilst this post-boom interval of stock development stalls out, it has finished sufficient to convey us right into a window the place nationwide resale residence worth development is now under U.S. revenue development (+3.4%), slowly serving to to easy over the overheating that occurred throughout the pandemic housing increase.
The place energetic stock/months of provide has risen probably the most, homebuyers have gained probably the most leverage. Generally speaking, housing markets the place stock (i.e., energetic listings) has returned to pre-pandemic 2019 ranges have skilled weaker residence worth development (or outright declines) over the previous 48 months. Conversely, housing markets the place stock stays far under pre-pandemic 2019 ranges have, typically talking, skilled stronger residence worth development over the previous 48 months.
Brown = Lively housing stock on the market in June 2026 was under pre-pandemic 2019 ranges
Inexperienced = Lively housing stock on the market in June 2026 was above pre-pandemic 2019 ranges
Click here for an interactive model of the map under.
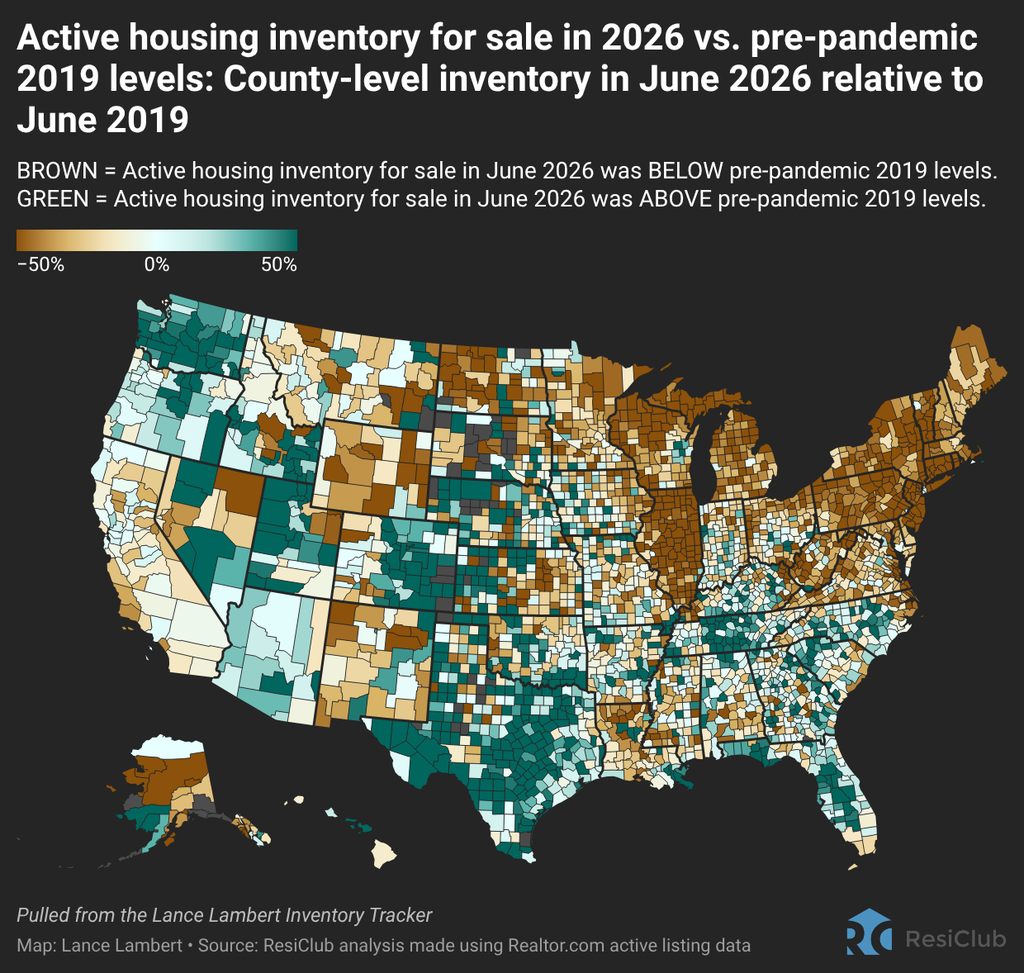
As ResiClub has carefully documented, that image varies considerably throughout the nation: A lot of the Northeast and Midwest stay under pre-pandemic 2019 stock ranges, whereas many components of the Mountain West and Gulf areas have bounced again.
Lots of the softest housing markets, the place homebuyers have gained probably the most leverage over the previous 4 years, are positioned in Gulf Coast and Mountain West areas.
These areas had been among the many nation’s prime pandemic boomtowns, having skilled vital residence worth development throughout the pandemic housing increase, which stretched housing fundamentals far past native revenue ranges. When pandemic-fueled home migration slowed and mortgage charges spiked, markets like Cape Coral, Florida, and San Antonio, Texas, confronted challenges as they needed to depend on native incomes to maintain frothy residence costs.
The housing market softening in these areas was additional accelerated by larger ranges of recent residence provide within the pipeline throughout the Sunbelt. Builders in these areas are sometimes prepared to cut back costs or make different affordability changes to keep up gross sales in a shifted atmosphere. These changes within the new building market additionally create a cooling impact on the resale market, as some patrons who might need opted for an current residence shift their focus to new houses the place offers are nonetheless obtainable.
In distinction, many Northeast and Midwest markets had been much less reliant on pandemic migration and have much less new residence building in progress. With decrease publicity to that home migration pullback demand shock—and fewer builders doing massive affordability changes to maneuver product—energetic stock in these Midwest and Northeast areas has remained comparatively tight—with residence sellers retaining extra energy relative to their friends within the Gulf and Mountain West areas.
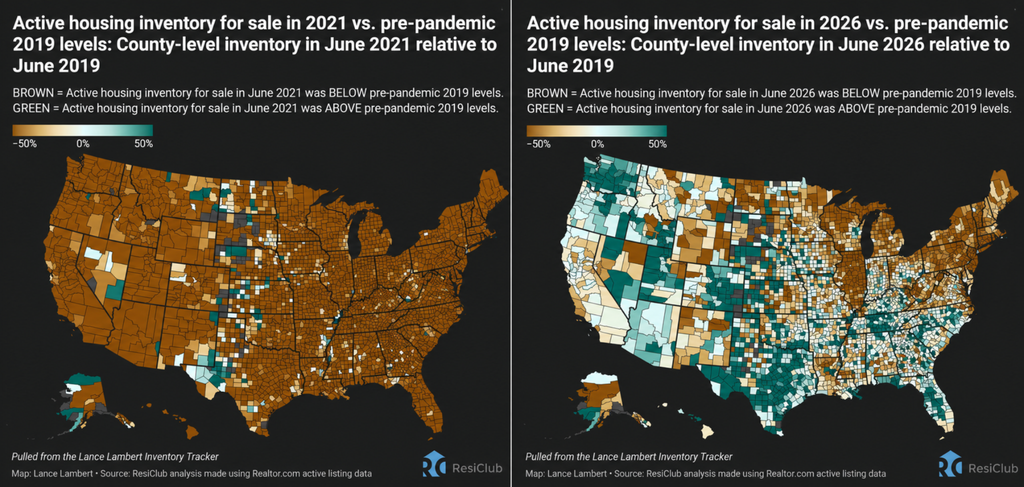
Whereas national active inventory on the finish of June 2026 was nonetheless 9.6% under pre-pandemic June 2019, it’s a lot nearer than it was in June 2021, when it was 59.6% under pre-pandemic June 2019.
Large image: The housing market continues to be grinding by way of a strategy of normalization following the surge in housing demand throughout the pandemic housing increase, when residence costs went up an excessive amount of, too shortly. Thus far, that normalization course of has pushed some markets—together with Austin (mid-2022 to current), Las Vegas (second half of 2022), Phoenix (second half of 2022), Boise (mid-2022-2023), Punta Gorda (2022 to current), Cape Coral (2023 to current), and Tampa, Florida (2024 to current)—into correction mode. In another areas to this point, it has triggered residence worth development to stall out.
In the meantime, some markets nonetheless stay tight and have solely seen a deceleration in residence worth development from the highs of the pandemic housing increase. As this occurs, and nationwide incomes proceed to rise (3.4% year over year), it’s slowly bettering underlying fundamentals and smoothing over the overheating that occurred throughout the pandemic housing increase.
